
 +965 2292 4888


Daily Economic Update
08.10.2026
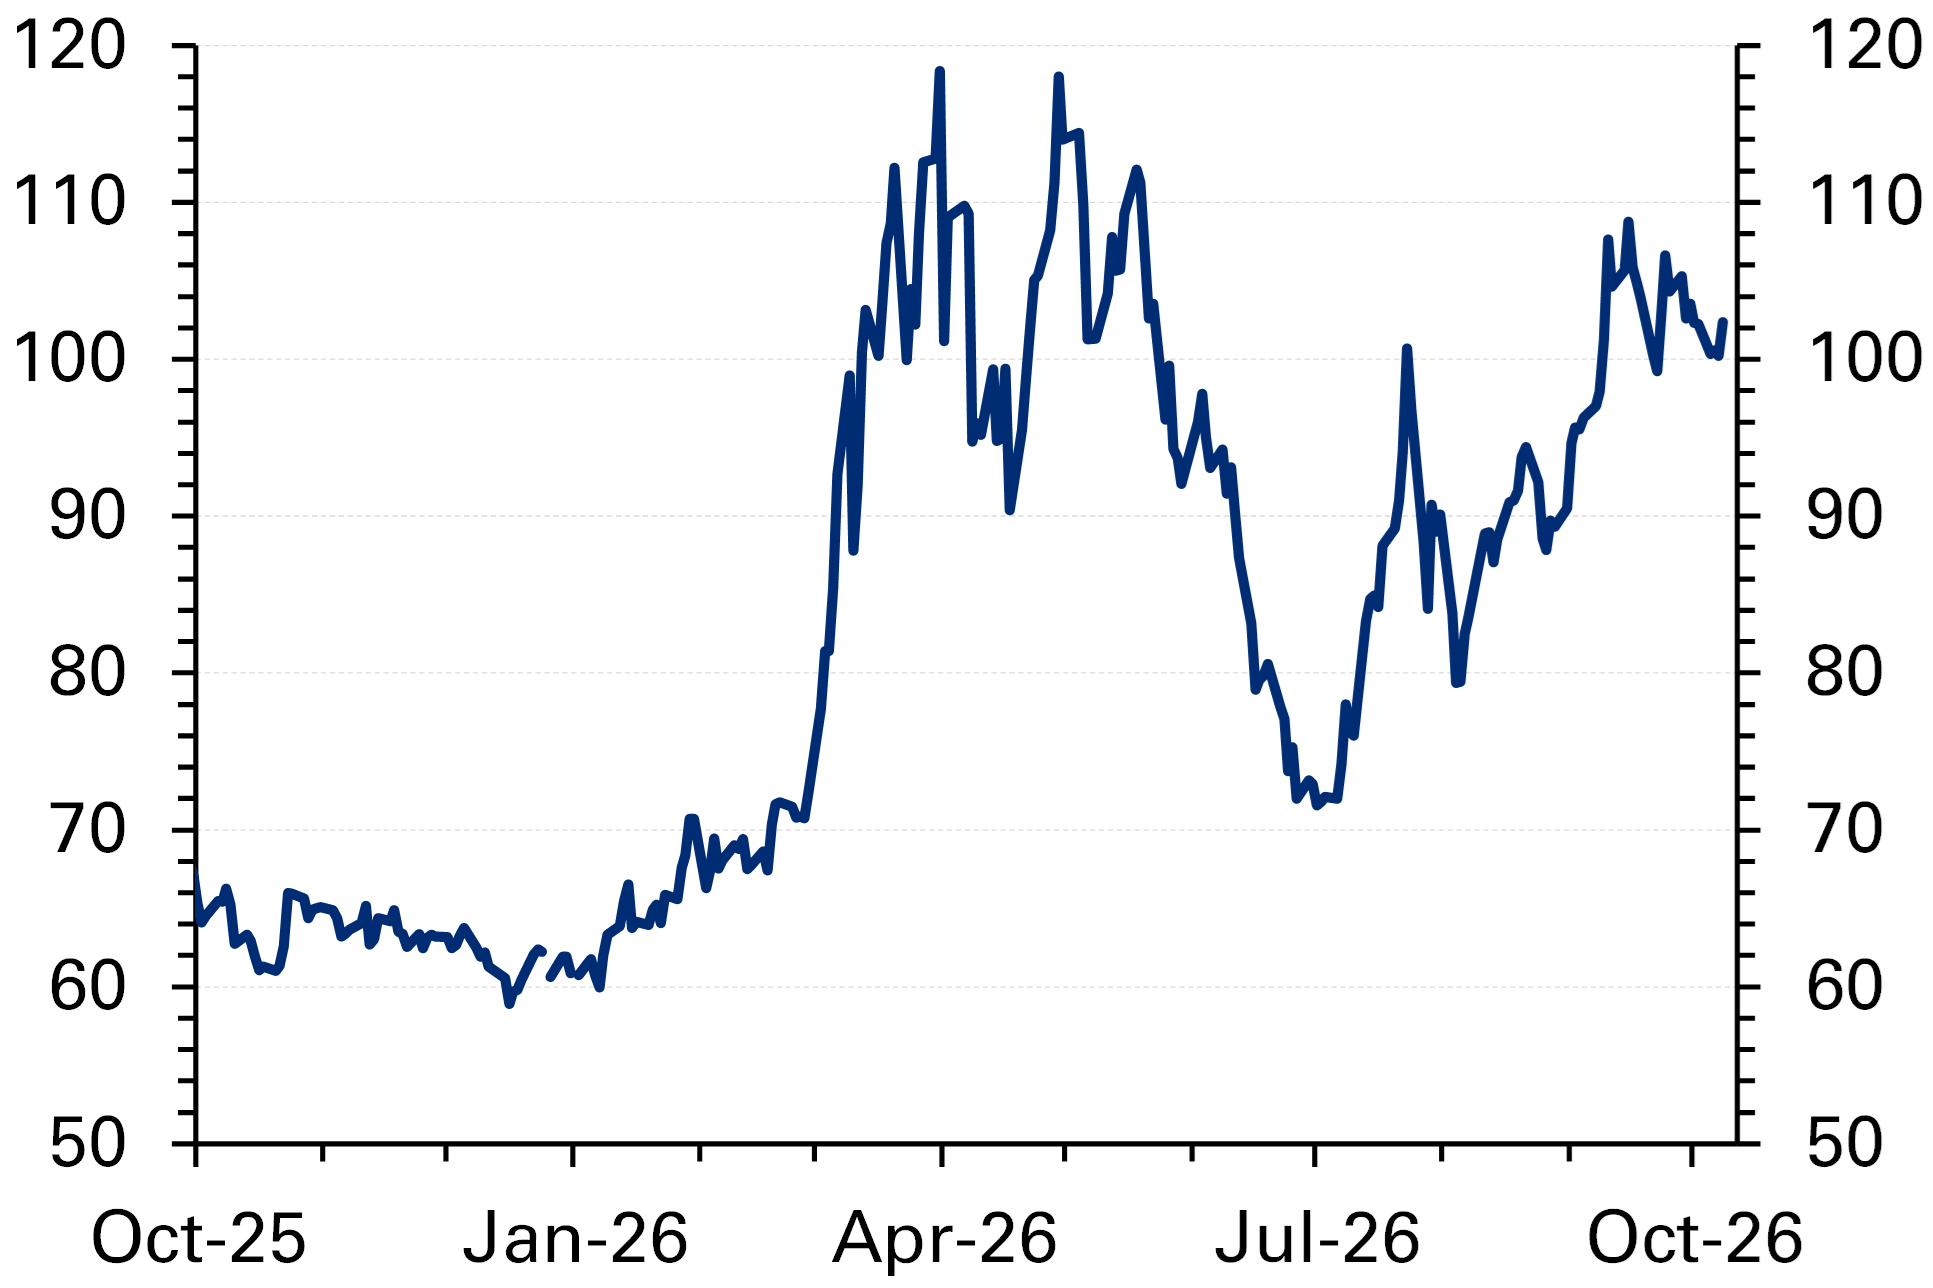
Oil: Prices gain in early trading as Gulf shipping comes under attack. Brent futures opened higher this morning, rising more than 2% to $102.4/bbl in Asian trading after a spike in attacks on Gulf shipping and Saudi infrastructure on Wednesday and on a report that the US administration was weighing up military strike options against Iran before the US mid-terms on November 3. Yesterday a tanker was hit by projectiles off the coast of Qatar, causing casualties, the UK Maritime Trade Operations reported, which would be the farthest north from the Strait of Hormuz a vessel has been targeted in more than month and the ninth so far this month—half the total for the entire month of September. Meanwhile, the Houthis on Wednesday also stepped up their attacks on Saudi Arabia, hitting two airports and killing three people. The Houthi riposte was in response to the apparent success the Saudi-backed Yemeni government has had recently in recovering strategic territory around the Bab-el-Mandeb lost to the militant group last month. The increase in Iranian attacks on Gulf shipping has served to puncture any sense of complacency the markets may have been feeling given the increase in oil flows through the Strait of Hormuz, which have risen to their highest level since the conflict. It may also be interpreted as a sign of desperation by the Iranian regime under the extreme economic pressure the US has been subjecting them to with their maritime blockade. Meanwhile, International Energy Agency (IEA) member countries have reiterated their support for the accelerated release of oil from their strategic reserves, with the drawdown of diesel stocks given the priority in view of the tightness of that segment of the market. The IEA confirmed that of the +400 mb pledged in the March 2026 Collective Action, 325 mb has been released to date.
US: FOMC officials expect another rate hike this year, September meeting minutes show. Minutes from the FOMC’s September meeting, when members unanimously voted to raise the policy interest rates by 25bps, showed that members were generally hawkish about the interest rate path ahead. The minutes noted that “most participants assessed that another increase in the target range for the federal funds rate would likely be appropriate by year end.” However, they cautioned that they would approach “each meeting with an open mind and decisions at future meetings would depend on incoming information”. Many participants emphasized that “despite the recent rise in longer-term Treasury yields, financial conditions appeared to be supportive of economic growth, with equity prices having risen substantially this year and spreads on corporate bonds having remained narrow,” and several members saw “the current policy rate as not restrictive or only mildly restrictive.” FOMC members also mentioned that geopolitical conflicts and resulting increases in energy products and surging AI-related investments were contributing to inflationary pressures and viewed the labor market as close to “maximum employment”. These views echo the recent commentary from several Fed officials. The latest dot-plot, in which 16 out of the 18 members who submitted their dots, indicated that another rate hike is expected by the end of 2026, following September’s move. After cautious remarks from some influential FOMC members recently and a relatively soft September jobs report, the market probability for a rate hike in October has fallen from over 70% at one point to around 18% now, but the futures market still signals an almost 80% probability of a hike by end-2026.
UK: House prices steady in September after August’s drop according to Lloyds Bank data. UK house prices were unchanged m/m and y/y in September following a drop of 0.3% m/m or 0.4% y/y in August as per the Lloyds Bank house price index. Separate data from the Royal Institution of Chartered Surveyors showed its UK house price balance slipping further to -32 from -28 in August, with downward price pressures most pronounced in London but prices rising in some regions outside. The residential property market has generally remained subdued, impacted by rising inflation, the anticipation of higher policy interest rates, a steep increase in market borrowing costs and a weak labor market. Though affordability is somewhat improving due to wage growth outpacing the increase in house prices in recent months, prospective buyers remain cautious. The Burnham government has recently announced the “Your First Home” scheme to provide easier funding access to first-time home buyers, and that should help improve demand in the market. More details about the scheme should be provided in the upcoming budget on October 28.
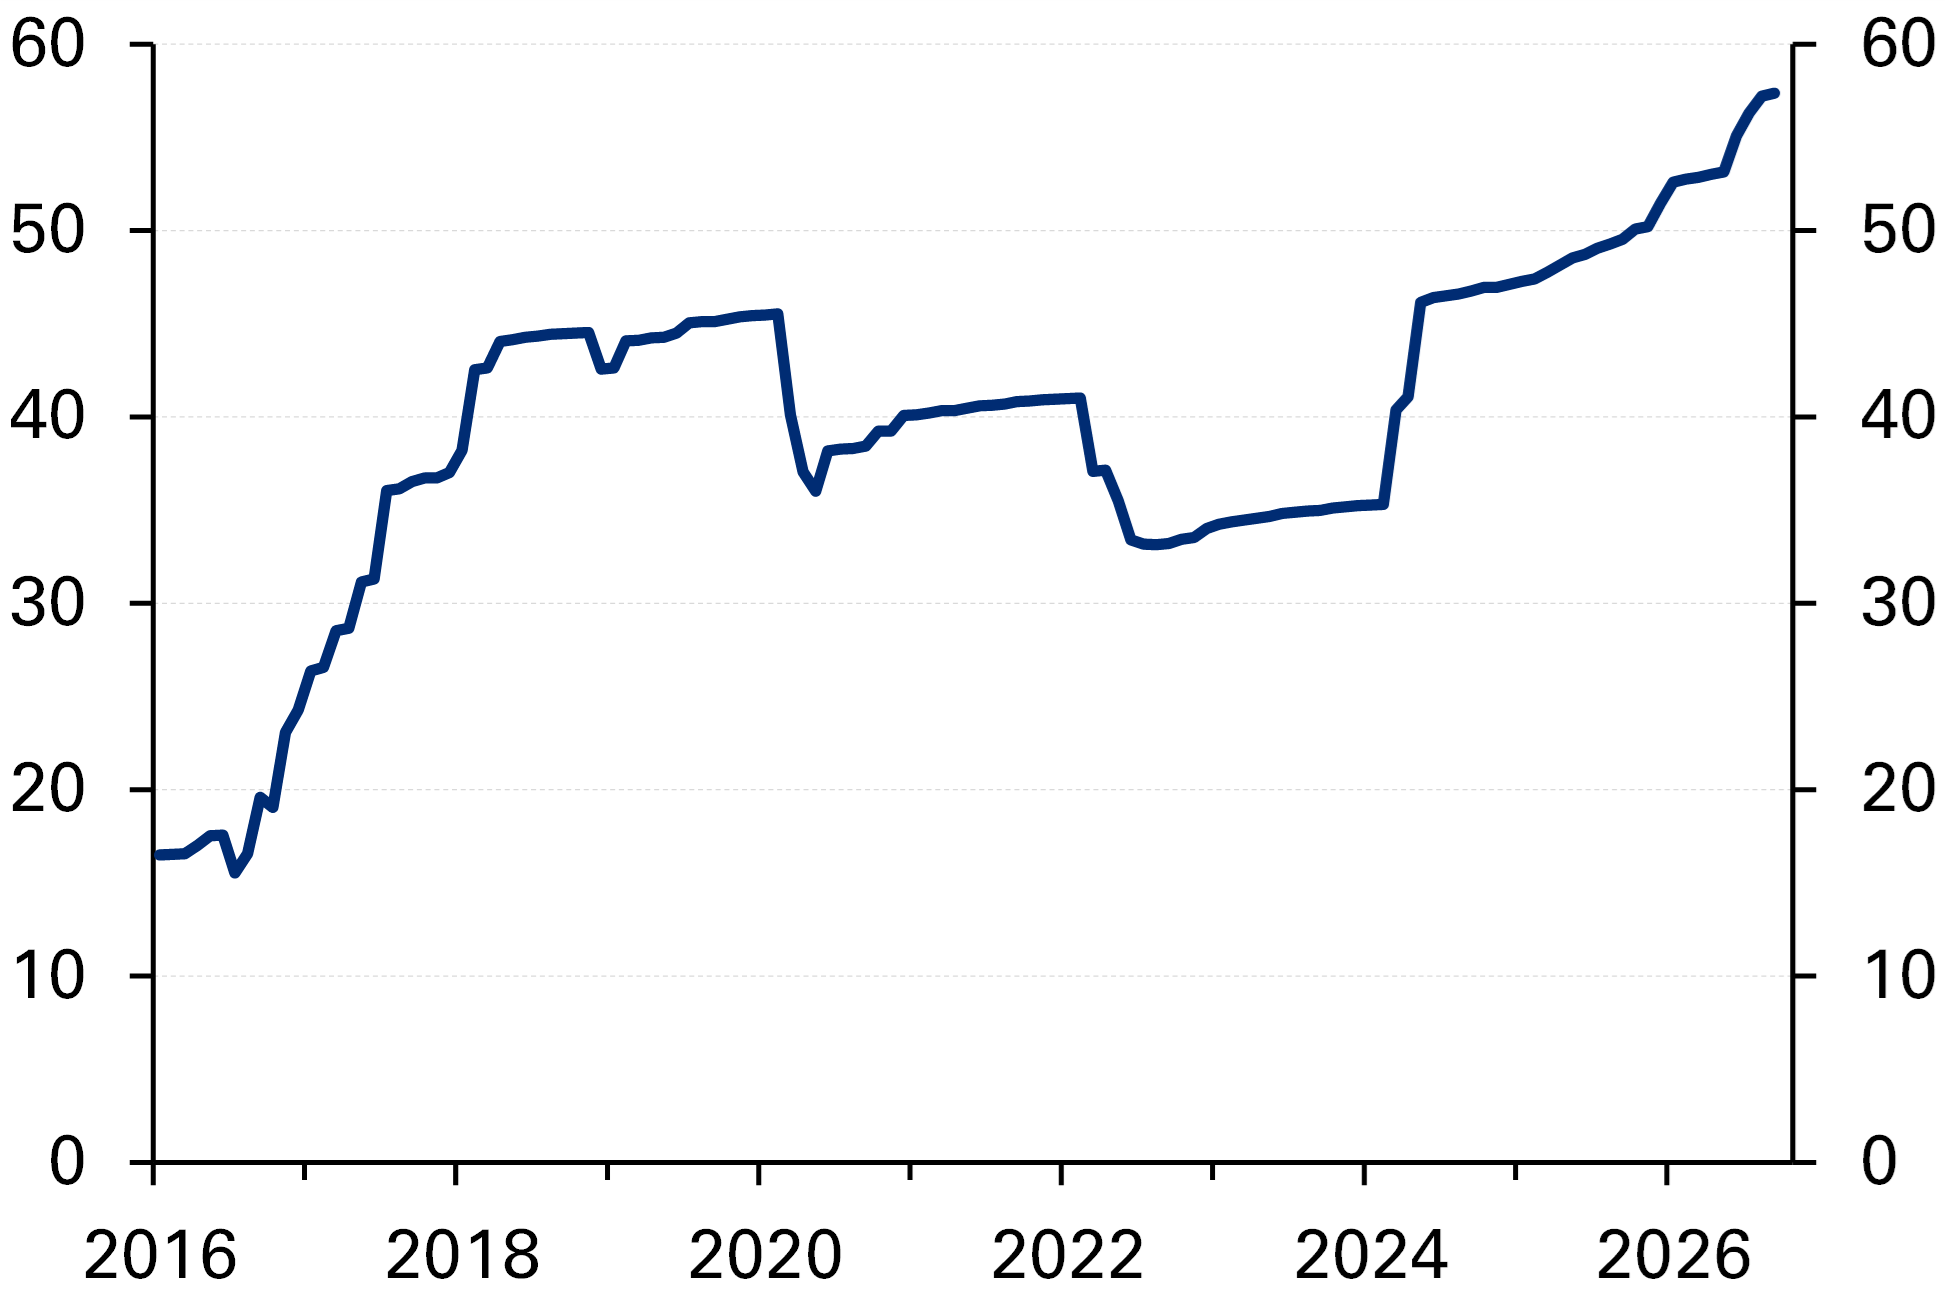
Egypt: Foreign reserves edge up again to new record high. Central bank data show that Egypt’s net foreign reserves edged up again in September, reaching a new record high of $57.3 billion from $57.2 billion in August. The move was driven by an increase in foreign currency reserves of $1.7 billion (to $39.3 billion), which more than offset a drop in the value of gold holdings of $1.6 billion (to $17.5 billion). Reserves have been trending higher since the currency devaluation of early 2024, when they stood at $35 billion and have also since been boosted by major FDI inflows, solid tourism and increased remittance flows. The IMF last month described reserve levels as being “comfortably above adequate levels”, despite initial outflows during the earlier stages of the US-Iran conflict. The steadily improving reserve picture has been underpinned by the move to a more flexible regime for the Egyptian pound, in which periods of softness no longer require major market intervention by the authorities to support the currency. The pound yesterday stood at EGP52.3/$1, some 11% below where it stood in pre-conflict November but still 4% stronger than its April low of EGP54.6/$1.