+965 2292 4888


Economic Insight
28.10.2026
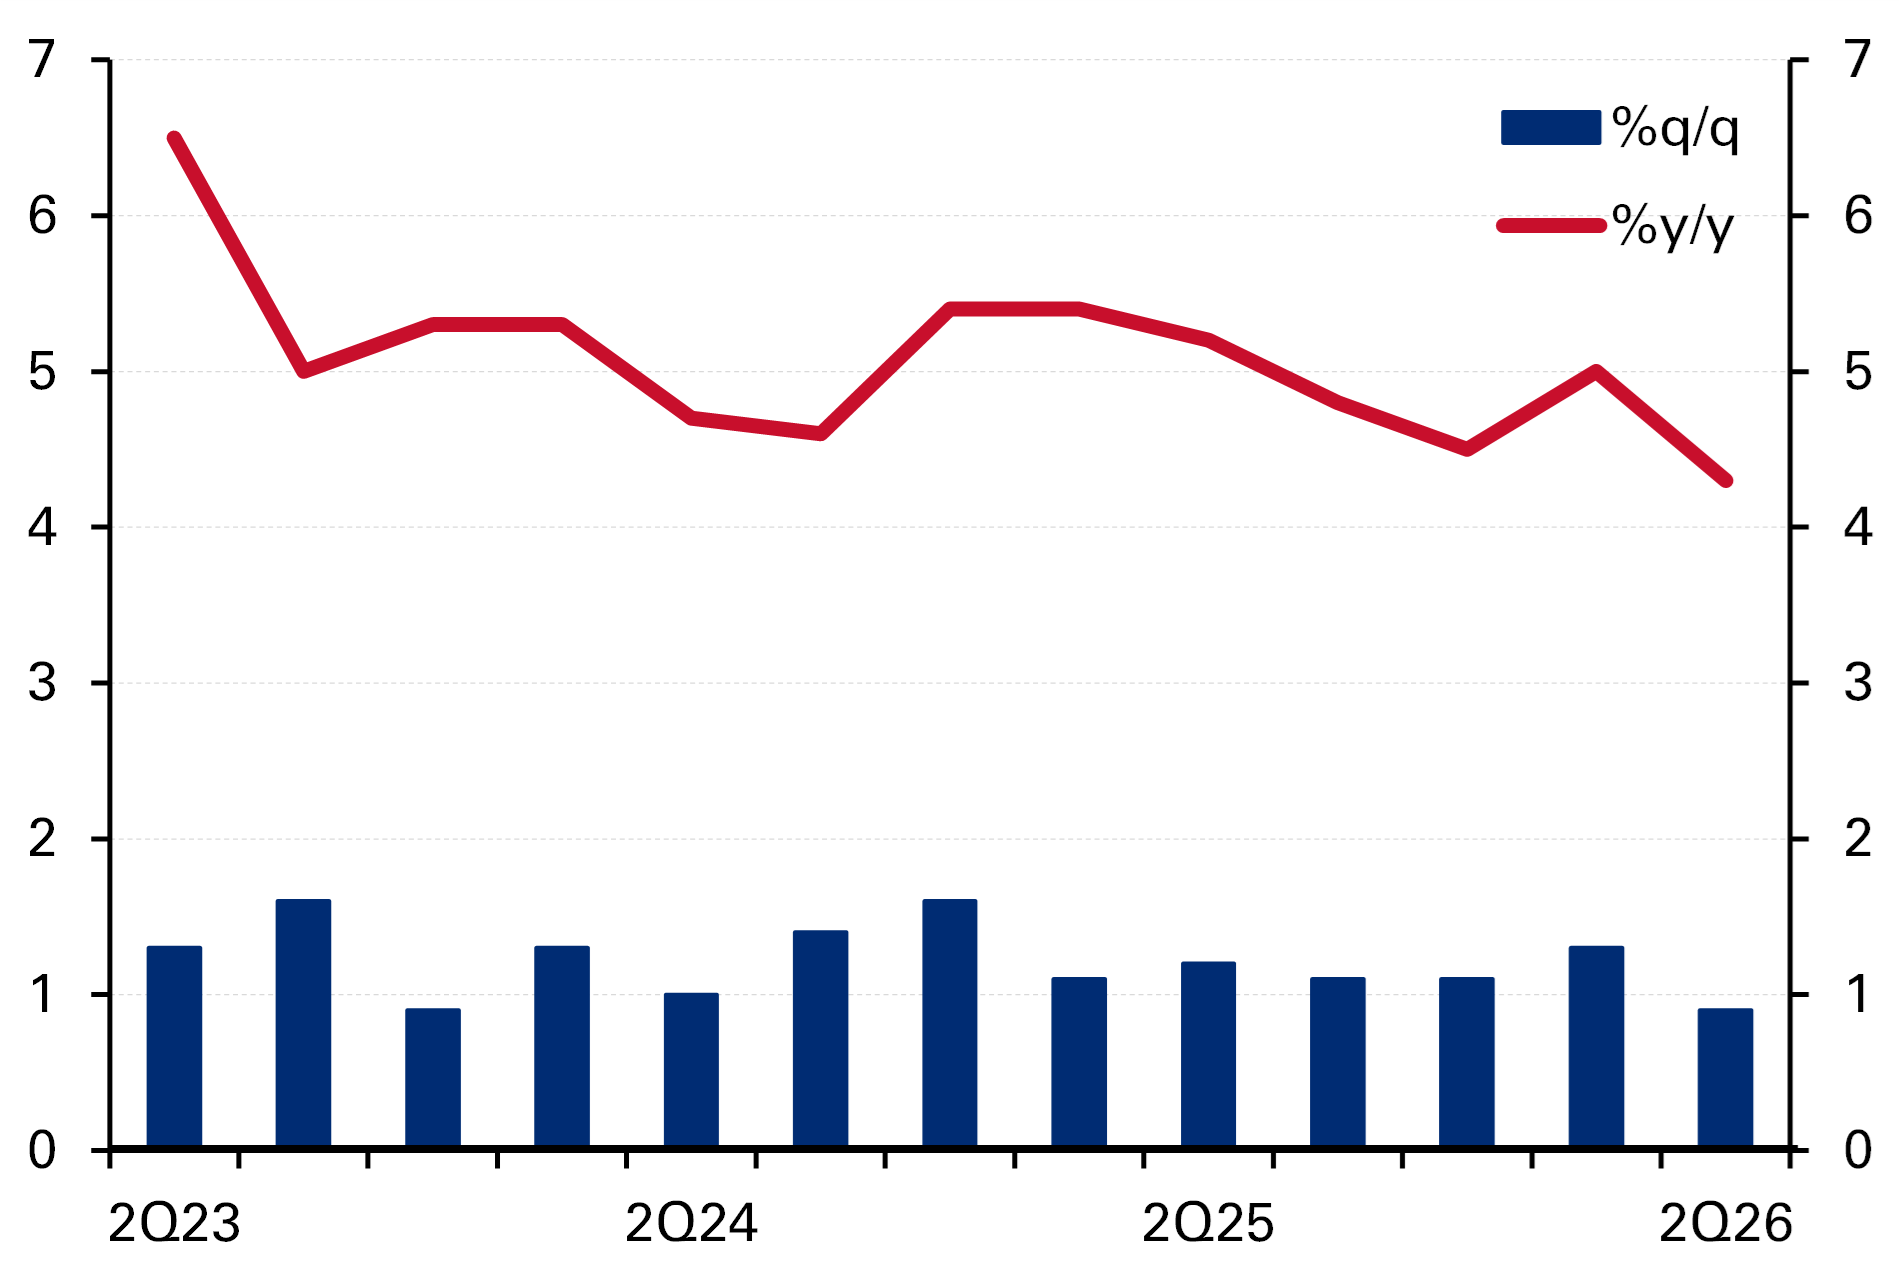
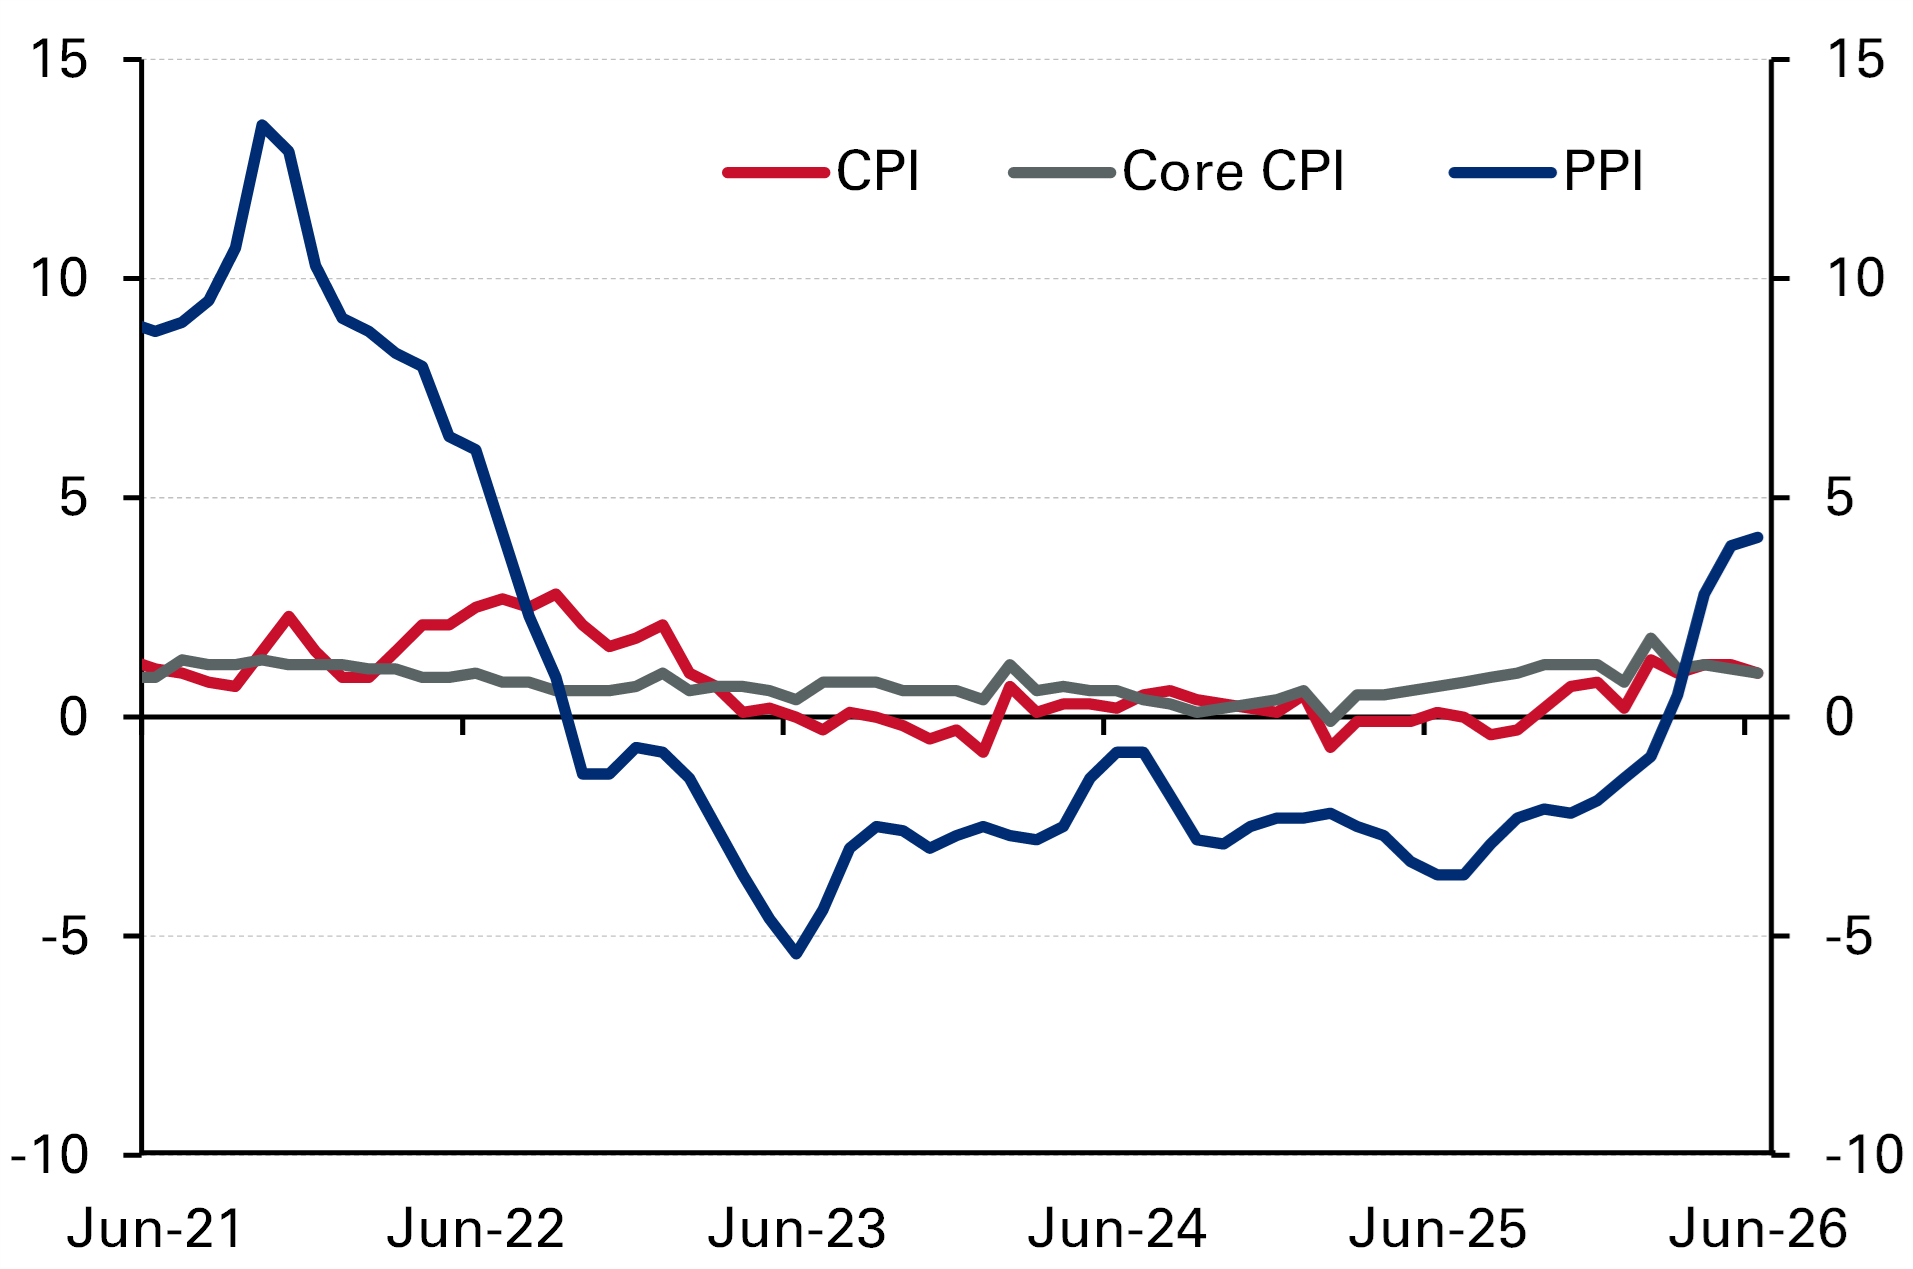
China’s economy (+4.6% y/y in 9M2026) remains on track to meet the government’s 4.5–5.0% growth target for this year, supported by resilient exports, strength in advanced manufacturing, a modest improvement in activity following the summer slowdown, and new stimulus measures announced last month. However, the focus is increasingly shifting from whether China can achieve its growth targets to whether policymakers can engineer a more balanced growth model. While external demand continues to provide an important source of support, domestic demand remains weak, with CPI inflation at a mere 0.9% y/y, investment activity subdued (-7.2% y/y in 9M2026), and the property sector (new house prices down 2.8% y/y in September) continuing to weigh on confidence and spending decisions. However, September activity data showed some improvement, with industrial production rising 5.5% y/y and retail sales increasing 1.1% y/y, both stronger than August and above expectations. The strength of exports has been impressive, surging by 36% y/y in September and driving growth in 9M2026 to more than 20%. The trade balance swelled to $938 billion in 9M2026, and is set to hit another annual record high in 2026. The recovery in exports to the US has been particularly remarkable, hitting levels in September that are in-line with pre-2025 trade-war levels.
Looking ahead, it is key to monitor the effectiveness of the stimulus measures introduced in recent weeks, including targeted fiscal and credit support, as well as efforts to stabilize the housing market. These policies should support growth in the remainder of 2026 and in 2027, reducing near-term downside risks. However, a sustained improvement in household consumption, private-sector confidence, and investment is needed for a more durable growth model. Without a stronger domestic growth engine, China’s economy is bound to remain heavily reliant on exports, leaving it overly exposed to changes in global demand.